The short answer
Five steps, in this orderInspect first
A documented inspection tells you whether there’s a claim worth filing, before anything goes on your record.
2checks
Most policies pay the actual cash value up front and hold the depreciation until the work is complete.
You choose
In Minnesota you choose your contractor. The insurer’s list is a convenience for them, not a requirement for you.
At a glance
Who does what, step by step
| Who | 01Inspection | 02File the claim | 03Adjuster meeting | 04The scope | 05Work & payment |
|---|---|---|---|---|---|
| You | Get the roof and siding looked at first | Call your carrier or use its app, and write the claim number down | Nothing— | Nothing— | Pay your deductible |
| North Point | Inspect and photograph, with a date | Nothing— | Meet the adjuster on the roof and walk it together | Compare it line by line, and send what’s missing as a supplement | Do the work as scoped and send the completion documents |
| Insurer | Nothing— | Gives you a claim number and assigns an adjuster | The adjuster inspects | Writes the estimate: the scope | Pays the actual cash value, then releases the depreciation |
01
Inspection before you call the insurer
Get the roof and siding looked at first. A documented inspection tells you whether there’s a claim worth filing and gives you photos with a date.
Why the order mattersFiling on a roof that turns out to have wear, not hail, still counts as a claim on your record.
Not sure what counts? Start with what hail damage actually looks like on a roof.
02
File the claim
Call your carrier or use its app. You’ll get a claim number and an adjuster will be assigned.
Write it down. It goes on everything after this.
03
The adjuster meeting
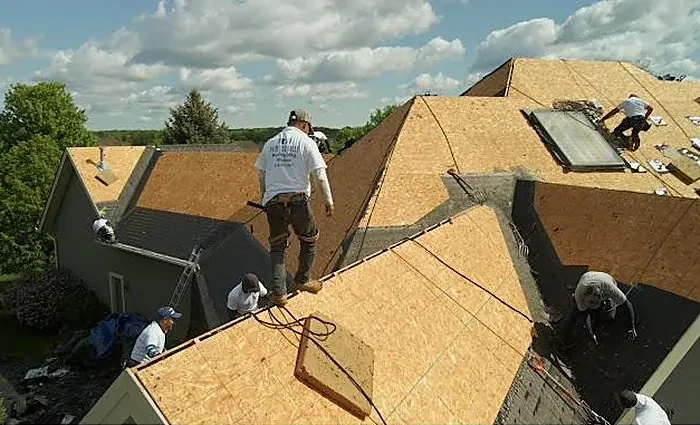
The adjuster comes out to inspect. We meet them on the roof. Not to argue — to make sure they see the same hits we photographed, on the same slopes, and to walk the metals, the siding, and any interior water damage together.
What we walk together
- The hits we photographed, on the same slopes
- The metals
- The siding
- Any interior water damage
Most disagreements later come from things nobody pointed out at this meeting.
04
The scope
The adjuster writes an estimate — the scope — of what the insurer will pay for. We compare it line by line to ours.
| Line item | Adjuster | Ours |
|---|---|---|
| Remove and replace the shingles | Included | Included |
| Drip edgeSupplement | Left off | Included |
| Ice-and-water shieldSupplement | Left off | Included |
| A code-required ventSupplement | Left off | Included |
| The interior drywallSupplement | Left off | Included |
Missing items (drip edge, ice-and-water shield, a code-required vent, the interior drywall) get submitted as a supplement with photos. This is normal and it’s most of what the paperwork is.
05
The work, then the final payment
Most policies pay in two parts: an actual-cash-value check up front, and the depreciation held back until the work is complete. We do the work as scoped, send the completion documents, and the second check releases.
How most policies pay
- 1The first check: the actual cash value, up front.
- 2We do the work as scoped and send the completion documents.
- 3The second check releases: the depreciation that was held back.
You pay your deductible and nothing beyond the approved scope unless you chose an upgrade.
06
What we won’t do
- Waive your deductibleThat’s insurance fraud in Minnesota.
- Pressure you at the doorWe don’t push you to sign anything at the door after a storm.
If someone does, that’s a storm chaser, and they’ll be in another state by the time the roof leaks.
07
Questions we get about this
Does the contractor deal with the insurance company for me?
We handle the documentation, meet the adjuster, and submit supplements. You stay the policyholder and the decisions stay yours; we just make sure the scope is complete.
Do I have to use the contractor the insurer recommends?
No. In Minnesota you choose your contractor. The insurer’s list is a convenience for them, not a requirement for you.
What if the adjuster’s estimate is lower than yours?
That’s what the supplement process is for. Differences are usually items left off, not disagreements about price, and they get resolved with photos and code references.